11 February, 2015

Analysis of the Black Scholes PDE

In this post we conduct a cursory analysis of the Black-Scholes (B-S) partial differential equation (PDE), including existence and uniqueness of solutions, well-posedness, and in certain special circumstances, analytical solutions.

The B-S PDE is defined the space positive half space $\mathbb{R}^{+}_{S}\times\mathbb{R}^{+}_{t}=\{(S,t): S\in(0,\infty),t\in(0,\infty)\}$ by the equation
$$(1)\;\;\;\;V_{t}+\frac{1}{2}\sigma^{2}S^{2}V_{SS}+rSV_{S}-rV=0.$$

For various pay-off functions $f=f(S,t)$ (where the $S$ in the argument is interpreted as $\{S_{t}\}_{t\in\mathbb{R}}$; in many cases it will just be $t=T$, the value of $S$ at expiration), boundary conditions may be instituted and the domain of definition becomes $(0,S_{\text{max}})\times(0,T)$.  We shall discuss boundary conditions in more detail later; for now we will work on the positive plane.

For $\xi\in\mathbb{R}$ we have
$$-\frac{1}{2}\sigma^{2}\xi^{2}<\theta\xi^{2}$$
for some appropriate positive parameter $\theta$ depending only on $\sigma$.  Thus, (1) is uniformly backward parabolic.

I.  Converting the B-S PDE to the heat equation (systematic procedure)

We begin our analysis by performing a sequence of change of independent and dependent variables in order to reduce the equation to a more simple one.  We first deal with the variable co-efficients, whose special structure suggests the change of variables $S\mapsto e^{-S}$, or using a new variable name, $x=\log S$.  The differential operators then become
$$\frac{\partial}{\partial S}=\frac{\partial}{\partial x}\frac{\partial{x}}{\partial S}=\frac{1}{S}\frac{\partial}{\partial x}$$
and
$$\frac{\partial^{2}}{\partial S^{2}}=\frac{\partial}{\partial S}\left[\frac{1}{S}\frac{\partial}{\partial x}\right]=\frac{1}{S^{2}}\left(\frac{\partial}{\partial x^{2}}-\frac{\partial}{\partial x}\right).$$
Substituting these into (1) yields
$$V_{t}+\frac{1}{2}\sigma^{2}(V_{xx}-V_{x})+rV_{x}-rV=0,$$
or
$$V_{t}+\frac{1}{2}\sigma^{2}V_{xx}+(r-\frac{1}{2}\sigma^{2})V_{x}-rV=0.$$

The reaction term $rV$ will lead to an exponential increase in the solution, and so we assume $V$ has the form $e^{rt}u$ for some to be determined function $u$.  This leads to the change of variables $V\mapsto e^{rt}u$ and the equation becomes
$$e^{rt}\left(ru+u_{t}+\frac{1}{2}\sigma^{2}u_{xx}+(r-\frac{1}{2}\sigma^{2})u_{x}-ru\right)=0,$$
or
$$u_{t}+\frac{1}{2}\sigma^{2}u_{xx}+(r-\frac{1}{2}\sigma^{2})u_{x}=0.$$

(If $r=r(t)$ is not constant, but a deterministic function of $t$ alone, then we can solve the ODE $w_{t}-r(t)w=0$ and make the change of variables $V=w(t)u$ in order to eliminate the source term; we will assume however that $r\equiv\text{const}$ for the remainder of this article.)

We now deal with the drift term $(r-\frac{1}{2}\sigma^{2})u_{x}$ by switching to the moving frame $x'=x-(r-\frac{1}{2}\sigma^{2})t$ (i.e. switching to the characteristic coordinate system).  We also at this stage change the structure of the equation to forward parabolic by changing the direction of evolution to forward time through the change of variables $t\mapsto -t$, or $t'=-t.$  We compute as before the new differential operators
$$\frac{\partial}{\partial x}=\frac{\partial}{\partial x'}\frac{\partial x'}{\partial x}+\frac{\partial}{\partial t'}\frac{\partial t'}{\partial x}=\frac{\partial}{\partial x'},$$
$$\frac{\partial^{2}}{\partial x^{2}}=\frac{\partial^{2}}{\partial x'^{2}},$$
$$\frac{\partial}{\partial t}=\frac{\partial}{\partial x'}\frac{\partial x'}{\partial t}+\frac{\partial}{\partial t'}\frac{\partial t'}{\partial t}=-(r-\frac{1}{2}\sigma^{2})\frac{\partial}{\partial x'}-\frac{\partial}{\partial t'}.$$

Substitution then yields
$$-(r-\frac{1}{2}\sigma^{2})u_{x'}-u_{t'}+\frac{1}{2}\sigma^{2}u_{x'x'}+(r-\frac{1}{2}\sigma^{2})u_{x'}=0$$
or
$$(2)\;\;\;\;u_{t'}-ku_{x'x'}=0.$$

This is the heat equation, with $k=\frac{1}{2}\sigma^{2}.$  It therefore suffices to study the properties of (1) by studying (2).

II. Uniqueness and Stability

We shall restrict our attention to the domain $D=\{(x,t):0\leq t\leq T,0\leq x\leq \ell\}.$ This is consistent with domain used in practice with solving (1).  We have the following theorem
Maximum Principle.  If $u$ solves the heat equation $u_{t}=ku_{xx}$, then $u$ achieves its maximum on the boundary lines $t=0$, $x=0$, or $x=\ell$.  Moreover, if $u$ achieves its maximum in the interior of $D$ or on the line $t=T$, then $u$ is constant.
The first assertion is what is known as the weak maximum principle, and this is what we shall prove.  The second assertion is called the strong maximum principle since it implies the weak version; however, its proof requires tools from the theory of harmonic functions (e.g. the mean-value property) and some non-trivial analysis (cf. Evans).  Analogous statements hold for the minimum by considering $-u$.

Proof.  Recall from calculus that if a function $u$ obtains its maximum at an interior point of a set $E$, then $D_{i}u=0$ and $D^{2}_{i}u\leq0$.  Therefore we have $u_{t}=0$ and $u_{xx}\leq0$.  The idea is to show that $u_{xx}<0$ in order to obtain a contradiction, and we will do this with a perturbation.

Let $\epsilon>0$, put $M=\sup_{(x,t)\in\partial D-\{(x,t):t=T\}}u$, and define $v:=u+\epsilon x^{2}.$ The definition of $v$ shows
$$(3)\;\;\;\;v_{t}-kv_{xx}=u_{t}-ku_{xx}-2\epsilon k=-2\epsilon k<0.$$
Applying the argument in the first paragraph shows that $v$ does not attain its maximum in $D^{\circ}$.  Suppose now $u$ obtains its maximum at a point $(x_{0},T)$ on the line $t=T$.  Then $v_{x}=0,v_{xx}\leq0$ as before and
$$v_{t}(x_{0},T)=\lim_{\delta\to0^{+}}\frac{v(x_{0},T)-v(x_{0},T-\delta)}{\delta}\geq0,$$
a contradiction.  Since $D$ is compact, the continuous function $v$ must obtain its maximum on $\partial D-\{(x,t):t=T\}.$  Therefore $v\leq M+\epsilon\ell^{2}$ on $D$.  By sending $\epsilon\to0$, we obtain the assertion of the weak maximum principle for $u$.

This theorem immediately settles the uniqueness of the boundary value problem for (2), for suppose $u$ and $v$ are both solutions to (2) with identical boundary data. Then $w:=u-v$ is also a solution by linearity has vanishes on the boundary $x=0,x=\ell,t=0$.  Thus $w\equiv0$ in all of $D$ by combining the assertions of the maximum and minimum principles.  This implies $u\equiv v$ and the claim follows.

Another important route to establishing uniqueness is through the concept of conservation of energy.

Consider the "energy" integral
$$E(t)=\int_{0}^{\ell}|u(x,t)|^{2}\;dx$$
where $u$ vanishes on the spatial boundary $0\leq x\leq\ell$ and at the intial time $t=0$.  Differentiating with respect to $t$ yields
$$E'(t)=\frac{d}{dt}\int_{0}^{\ell}u^{2}\;dx=\int_{0}^{\ell}2uu_{t}\;dx.$$
where differentiation under the integral sign is valid, since as will be clear in the next section when we solve the heat equation, the mapping $x\mapsto 2u(x,t)u'(x,t)$ is absolutely integrable on $[0,\ell]$ for every $t\in[0,T)$.  Substituting $u_{t}=ku_{xx}$ and integrating by parts yields
$$E'(t)=2k\int_{0}^{\ell}uu_{xx}\;dx=2kuu_{x}\Big|_{x=0}^{x=\ell}-2k\int_{0}^{\ell}u^{2}_{x}\;dx=-2k\int_{0}^{\ell}u_{x}^{2}\;dx\leq0.$$
However, $E(0)=0$, and therefore $E\equiv0$ for all $t$.  Consequently, $u\equiv0$ and by considering the difference of two solutions with identical boundary data, we recover uniqueness (initially, we have uniqueness only almost everywhere, but since solutions to the heat equation are smooth, we recover pointwise uniqueness.)

We continue our efforts to establish well-posedness by showing that the PDE is stable with respect to the initial and boundary data.

III. Existence and the fundamental solution

There are by now multiple approaches to solving the heat equation recorded in the literature.  One of the simplest makes use of the Fourier transform.  We begin by extending our spatial domain to all of $\mathbb{R}$ and enforcing a decay condition so that $u\in L^{2}(dx).$  Our convention for the (one-dimensional) Fourier transform is
$$\mathcal{F}(u)(\xi):=\hat{u}(\xi)=(2\pi)^{-1/2}\int_{-\infty}^{\infty}u(x)e^{-ix\xi}\;dx$$
so that
$$||\hat{u}||_{2}=||u||_{2}\;\;\;\;(\text{Plancheral})$$
along with the associated inversion formula
$$u(x)=\int_{-\infty}^{\infty}\hat{u}(\xi)e^{ix\xi}\;d\xi.$$

The Fourier transform drops polynomial weights in exchange for anti-differentiation, so we apply it to the spatial derivative $x$ in order to get

$$\hat{u}_{t}=-k|\xi|^{2}\hat{u}.$$

Note that we have used the relation $\mathcal{F}(\partial_{t}u)=\partial_{t}\mathcal{F}u,$ which holds because of our condition on $u$.

Solving this ODE (in $t$) yields
$$\hat{u}=\hat{u}(0)e^{-k\xi^{2}t}.$$

A simple computation involving substituting the above result into the inversion formula and applying the convolution theorem then yields

$$u(x,t)=(4\pi kt)^{-\frac{1}{2}}\int_{-\infty}^{\infty}\phi(x)e^{-(x-y)^{2}/4kt}\;dy,$$
where $\phi(x)=u(x,0).$  This implies that our fundamental solution is
$$\Phi(x,t)=(4\pi kt)^{-\frac{1}{2}}e^{-x^{2}/4kt}.$$

IV. Boundary conditions and special solutions to the B-S PDE

Let us examine some typical boundary conditions in the Black-Scholes PDE.

07 February, 2015

Explicit Finite Difference Method for Black-Scholes-Merton PDE (European Calls)

Here we will implement a basic finite difference method to the solution of the Black-Scholes-Merton PDE
$$(1)\;\;\;\;\frac{\partial V}{\partial t}+\frac{1}{2}\sigma^{2}S^{2}\frac{\partial^{2}V}{\partial S^{2}}+rS\frac{\partial V}{\partial S}-rV=0,$$
which of course models the value $V$ of any derivative contract in the absence of arbitrage (see the Wikipedia article for a more comprehensive list of assumptions under which the Black-Scholes-Merton model is valid).

This PDE is a backwards diffusion (parabolic) equation: it is ill-posed in forward time.  This means that "initial conditions" are prescribed at $t=T$, the expiry time of the derivative being priced (in the case of this article, an option).  This is analogous to the prototypical heat equation $u_{t}=\Delta u,$ which is ill-posed in backward time, and hence requires initial conditions to be prescribed at time $t=0$.  It makes sense that a reverse-time evolution equation would model the value of a derivative since the payoff of the conract is known at the time of expiry $t=T$, and it is at the initial time $t=0$ that we are interested in knowing the "correct" value of the contract.  Indeed, we assume that the underlying of the derivative is a stock which follows a geometric Browning motion $\{S_{t}\}_{t\geq0}$ as in the Black-Scholes-Merton model.  This is a stochastic process for which we know $S_{0}$ (the time that the contract is being sold) and so the Black-Scholes equation allows us to compute $V(S(t),t)\big|_{t=0}=V(S_{0},0)$, which is the value of the contract today with observed stock price $S_{0}$.

The above discussion gives us an indication as to what boundary conditions must be prescribed in order that the solution $V(S,t)$ corresponds to the particular derivative contract being valued.  Indeed, (1) gives the value of any derivative; it is the boundary conditions which specify which derivative.  We shall consider the PDE to be defined on the $(S,t)$ space $[0,\bar{S}]\times[0,T]$ where $\bar{S}$ is the maximal stock price (typically $\bar{S}$ is taken to be $\bar{S}\approx 3K$, where $K$ is the strike price of the option).  (Ideally, we would have $\bar{S}=\infty$ so that we could apply the natural bounary condition $V(S,t)\to S$ as $S\to\infty$, but we must use a finite domain when applying finite differences.)  We then have the following boundary-value problem corresponding to (1)

$$\left\{\begin{array}{ll}
\frac{\partial V}{\partial t}+\frac{1}{2}\sigma^{2}S^{2}\frac{\partial^{2}V}{\partial S^{2}}+rS\frac{\partial V}{\partial S}-rV=0,&0\leq t< T, 0<S<\bar{S}\\
V(S,T)=\max(S-K,0),&t=T\\
V(0,t)=0,&S=0\\
V(\bar{S},t)=\bar{S}-Ke^{-r(T-t)},&S=\bar{S}.\end{array}\right.
$$

We now discretize the domain into increments $\Delta S$ and $\Delta t$.  The following notation is used: $k=\Delta t$, $h=\Delta S,$ $V_{m}^{n}=V(mh, nk),$ $N=T/k$, $M=\bar{S}/h.$  For simplicity we start with forward differences in time and centered differences in space to get (after some algebra)
$$V_{m}^{n}=A_{m}V_{m-1}^{n+1}+B_{m}V_{m}^{n+1}+C_{m}V_{m+1}^{n+1}$$
where
$$\begin{array}{l}
A_{m}=\frac{k}{2}\left(\sigma^{2}m^{2}-rm\right)\\
B_{m}=(1-k)(r\sigma^{2}m^{2})\\
C_{m}=\frac{k}{2}\left(\sigma^{2}m^{2}+rm\right)\end{array}
$$

Recall that the evolution is backward in time, so that this method is indeed explicit.

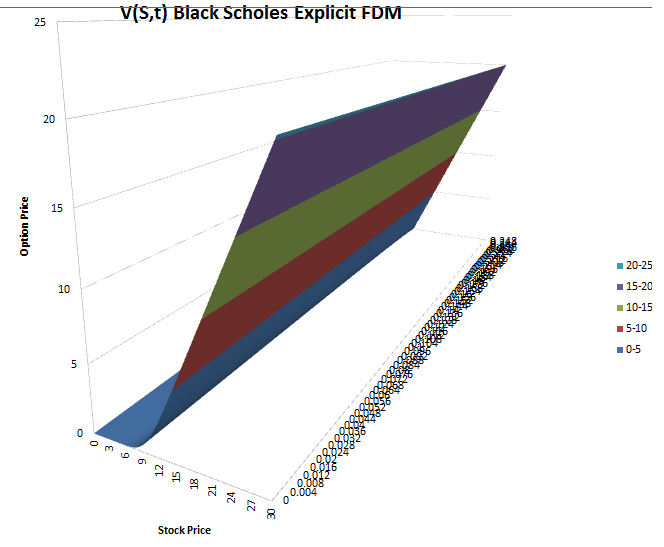
The following method was coded in Excel VBA using the method discussed above.  In this implementation we have used parameters $T=0.25$ (expiry in 3 months), $K=10$ (strike price 10 USD), $r=0.1$ and $\sigma=0.4.$

BS_FDM_Explicit.xlsm (Coded in Excel VBA)
Sub BSFiniteDifferenceScheme()

    ' User defined parameters
    Dim Riskless As Double
    Dim Vol As Double
    Dim Expiry As Double
    Dim Strike As Double
    
    Riskless = 0.1
    Vol = 0.4
    Expiry = 0.25
    Strike = 10
    
    ' Finite difference parameters
    Dim T As Double ' final time
    Dim S As Double ' stock price upper limit
    Dim N As Integer ' temporal steps
    Dim M As Integer ' stock steps
    Dim k As Double ' time step
    Dim h As Double ' stock step
    Dim V() As Double ' solution V(s,t)
    Dim T_Array() As Double
    Dim S_Array() As Double
    
    ' Set preliminary parameters
    T = Expiry
    S = 30
    k = 0.001
    h = 0.5
    N = T / k
    M = S / h
    ReDim V(N, M)
    
    For i = N To 0 Step -1
        Cells(i + 2, 1) = i * k
    Next i
    For j = 0 To M
        Cells(1, j + 2) = j * h
    Next j
    
    ' Set left boundary condition (S=0)
    For i = N To 0 Step -1
        V(i, 0) = 0
        Cells(i + 2, 2) = V(i, 0)
    Next i
    
    ' Set upper boundary condition (t=T)
    For j = 0 To M
        If j * h > Strike Then
            V(N, j) = j * h - Strike
        Else
            V(N, j) = 0
        End If
        Cells(N + 2, j + 2) = V(N, j)
    Next j
    
    ' Set right boundary condition (S=S_max)
    For i = N To 0 Step -1
        V(i, M) = S - Strike * Exp(-Riskless * (T - i * k))
        'V(i, M) = S
        Cells(i + 2, M + 2) = V(i, M)
    Next i
    
    ' Computation Loop
    Dim A As Double
    Dim B As Double
    Dim C As Double
    For i = N - 1 To 0 Step -1
        For j = 1 To M - 1
            A = (k / 2) * (Vol ^ 2 * j ^ 2 - Riskless * j)
            B = 1 - k * (Riskless + Vol ^ 2 * j ^ 2)
            C = (k / 2) * (Vol ^ 2 * j ^ 2 + Riskless * j)
            V(i, j) = A * V(i + 1, j - 1) + B * V(i + 1, j) + C * V(i + 1, j + 1)
            Cells(i + 2, j + 2) = V(i, j)
        Next j
    Next i
   
End Sub
The output has been setup to give the value of $V(S,t)$ for any pair $(S,t)$.  The table of data is of course to large to be given here, and of course we are only interested in the data $V(S_{0},0)$ where $S_{0}$ is the spot price at $t=0$.  For example, when $S_{0}=20$ the computation gives $V(20,0)=10.25$ USD.  This is the price at time $t=0$ for the option to buy a stock at time $T=0.25$ years when the current spot price is $20$ USD and the strike price is $10$ USD.  This rather high price (relative to the stock price) makes sense considering that the option is deep in the money and likely to be exercised at expiry.  To check that our value is indeed correct, we run the Monte Carlo simulation discussed in this post with identical parameters; the computed value with $N=10000$ trials is $V=10.21$ USD.  If we increase $N$ to $N=1000000$ (one million), we get with much greater consistency $V=10.25$, which is in agreement with our finite difference computation.
A graph produced from the output in Excel is given below.


The orientation has been adjusted so that the solution curve at $t=0$ is clearly visible (the one of interest).

04 February, 2015

Exact pricing formula for a binary put or call

Consider a contract that pays $B=1$ if $S(T)\geq K$ at the terminal time $T$ (and $B=0$ if $S(T)<K$), where $S$ follows the geometric brownian motion process
$$S(t)-S_{0}=\mu\int_{0}^{t}S(t)\;dt+\sigma\int_{0}^{t}S(t)\;dW(t).$$
In "differential" form,
$$dS_{t}=\mu S_{t}dt+\sigma S_{t}dW_{t}.$$

This contract is known as a binary call option.  We seek to determine its price $V$ at the initial time $t=0$.  

The Black-Scholes theory implies (through its connection to parabolic partial differential equations and the Feyman-Kac formula) that this price is equal to the risk-neutral expected payoff $\mathbb{E}_{\mathbb{Q}}$ discounted at the risk-free rate $r$.  That is,
$$V=e^{-rT}\mathbb{E}_{\mathbb{Q}}[B].$$

A simple computation reveals that this is equal to $e^{-rT}\mathbb{Q}(S_{T}>K)$.  In detail,


$$e^{rT}V=\mathbb{E}_{\mathbb{Q}}[B]=1\cdot\mathbb{Q}(B=1)+0\cdot\mathbb{Q}(B=0)=\mathbb{Q}(B=1)=\mathbb{Q}(S_{T}>K).$$

Now, as covered in the Black-Scholes theory, an application of Girsonov's theorem leads us to the equivalent process for $S$
$$dS=rSdt+\sigma Sd\tilde{W_{t}}$$
where $\tilde{W}$ is a Brownian motion under the equivalent martingale measure (risk-neutral measure) $\mathbb{Q}$.  We now proceed as usual taking the natural logarithm to get
$$d\log S=(r-\frac{1}{2}\sigma^{2})dt+\sigma d\tilde{W_{t}},$$
which, in light of the risk-neutral probability computation above, immediately leads us to
$$\mathbb{E}_{\mathbb{Q}}[B]=N(d_{2}),$$
where $N=\Phi(0,1)$, the standard normal density, and
$$d_{2}=\frac{\ln(S_{0}/K)+(r-\frac{1}{2}\sigma^{2})T}{\sigma\sqrt{T}}.$$
Thus,
$$V=e^{-rT}N(d_{2}).$$
The price of the put can be determined by following the steps above, but where the contract has a payoff of $1$ when $S(T)\leq K$.  The result is
$$V=e^{-rT}N(d_{1}),$$
or equivalently
$$V=e^{-rt}N(-d_{2}).$$

As an aside from this, we can compute the price of this option using only the known prices of European call options.  Observe that the payoff function $P$ of this option is given by
$$P=\frac{\partial C_{K}}{\partial S}$$
where $C$ is the payoff function for European call option with strike price $K$.
This observation leads us to the conclusion
$$V=\lim_{\delta\to0}\frac{{U(K-\delta})-U(K)}{\delta}=-\frac{\partial U}{\partial S},$$
where $U(K)$ is the value of the call option with strike $K$.

24 January, 2015

Forward Spot Rate Curves

Consider a vector of maturities $(m_{1},\ldots,m_{N})$ and corresponding spot (zero) rate vector at time $t\geq0$ (which could be obtained from bootstrapping for instance, or in the case of LIBOR rates already given):
$$\left(S_{t}^{(m_{1})},\ldots,S_{t}^{(m_{N})}\right).$$
This can be viewed as a stochastic process with state space $\mathbb{R}^{N}$ or as $N$ individual stochastic processes $\{S^{(m_{j})}_{t}\}_{t\geq0}$ for $m_{j}\in\{m_{1},\ldots,m_{N}\}$ with state space $\mathbb{R}$.  Corresponding to this process is a forward process
$$\left\{\left(f_{t}^{(m_{1})}(T),\ldots,f_{t}^{(m_{N})}(T)\right)\right\}_{t\geq0}$$
that has an extra (deterministic) dimension in the variable $T$ and therefore the forward process has state space $\mathcal{C}(\mathbb{R})^{N}$.  Let us isolate our attention to one component of this process, say $f_{t}^{(m_{j})}(T)$ for some $1\leq j\leq N$, the forward spot rate process corresponding to maturity $m_{j}$ and future time $T$.  How do we determine this process in terms of $S^{m_{j}}_{t}$ so that for each $T\geq0$ the usual arbitrage conditions are satisfied?  For a non-dividend paying stock, the process is given by
$$f_{t}(T)=S_{t}e^{r(T-t)}.$$
But there is no obvious analogue for interest rates.  In fact, $f_{t}^{(m_{j})}(T)$ will depend on two components of the spot rate process for each $T$.  The definition is
$$(1)\;\;\;\;f^{(m_{j})}_{t}(T)=\frac{S^{(T+m_{j})}_{t}(T+m_{j})-S^{(T)}_{t}T}{m_{j}}.$$
This is obtained by equating the cash flows of borrowing at $S^{(T+m_{j})}_{t}$ for $T+m_{j}$ years versus borrowing at $S^{(T)}_{t}$ for $T$ years and then rolling forward the returns at $f^{(m_{j})}_{t}(T)$ for $m_{j}$ years.  This of course restricts $T$ to the set $\mathcal{T_{j}}:=\{m_{i}\}_{1\leq i\leq N-k(j)}$ where $k(j)$ is such that $T+m_{j}\leq m_{N}$ for all $T\in\mathcal{T_{j}}$.

An equivalent and more commonly encountered way to express this is to write
$$(2)\;\;\;\;f^{(m_{j})}_{t}(T_{1},T_{2})=\frac{S^{(T_{2})}_{t}T_{2}-S_{t}^{(T_{1})}T_{1}}{T_{2}-T_{1}}.$$
In this case, we require $T_{2}-T_{1}=m_{j}$ and $m_{1}\leq T_{2}\leq m_{N}.$  Of course, if we are interested in a forward rate at time $T$ that is not compatable with the spot rate vector that we have available at time $t$, then we can interpolate the pot curve (although this could potentially lead to arbitrage opportunities if you (a bank, say) are using this forward curve to price fixed income derivatives such as a swaps, because it is conceivable that a potential arbitrageur could get a spot rate for that interpolated term date different from your interpolated value!).

If we compute (1) for all $T\in\mathcal{T}_{j}$ we get a vector of points that represents the forward curve for the spot rate $S^{(m_{j})}_{t}$ associated with term $m_{j}$ computed at time $t$.  If we then do this for each $1\leq j\leq N$, we get a set of forward curves, one for each spot rate term.  If we fix a $T$ and plot $f^{(m_{j})}_{t}(T)$ for each $m_{j}$, then we get a forward term structure curve corresponding to the forward time $T$.  The particular interpretation taken depends on the context; usually the former is used for evaluating swap derivatives and the ladder for evaluating bond derivatives.

16 January, 2015

Valuing European FX (Currency) Options

I. Overview

A currency option is a contract that gives the buying party the right, but not the obligation, to buy (call) or sell (put) a foreign currency at a pre-defined exchange rate (strike).

For a given currency pair (e.g. EURJPY), the call or put designation of the option contract always refers to the base currency; therefore, the foreign currency is the base currency and the domestic currency is the quoted currency.  For example, a Japanese company expects to make a payment of 1,000,000 Euros in six months; they can hedge this exposure (while also participating in favorable price movements) by purchasing a call option on EUR/JPY.  Similarly, if they expected to receive Euros, they'd enter into a put option on EUR/JPY.

Because of the nature of FX transactions, every currency option is technically two options: a call and a put.  So a call on EUR/JPY is a call (buy/receive) on EUR and a put (sell/give) on JPY for a specified exchange rate (the strike) and a put on EUR/JPY is a put (sell/give) on EUR and a call (buy/receive) on JPY.

Exercise.  Sometimes a currency pair is not actively quoted.  For example, if the domestic currency is EUR and the foreign currency is JPY, the pair underlying a given currency contract would be JPY/EUR, which is not actively quoted.  Of course, one could simply invert this currency pair and the above discussion applies with this exchange rate.  However, show that for currencies C1 and C2 that a call (put) on C1/C2 is a equivalent to a put (call) on C2/C1.  So if the European company (domestic currency) wants to buy a put on JPY/EUR (they want to sell JPY that they expect to receive sometime in the future for EUR), then they can buy an (equivalent) call on EUR/JPY.
As a final note, each currency has an associated risk free rate $r_{d}$ and $r_{f}$ (domestic and floating, respectively). 

 II. Valuation Theory

The Black-Scholes model on a dividend paying equity is easily adapted to the present situation by regarding the currency pair exchange rate as a price with an associated volatility and the foreign riskless rate as a dividend yield.  The justification for the ladder follows the same cost of carry argument as in the case of a dividend.

The usual formulas are
$$c(S,t)=Se^{-r_{f}(T-t)}\mathbb{N}(d_{1})-Ke^{-r_{d}(T-t)}\mathbb{N}(d_{2})$$
and
$$p(S,t)=Ke^{-r_{d}(T-t)}\mathbb{N}(-d_{2})-Se^{-r_{f}(T-t)}\mathbb{N}(-d_{1})$$
where of course
$$d_{1}=\frac{\log(S/K)+(r_{d}-r_{f}+\sigma^{2}/2)(T-t)}{\sigma\sqrt{T-t}}$$
and
$$d_{2}=d_{1}-\sigma\sqrt{T-t}.$$

Because $F_{t}=S_{t}e^{-(r_{d}r_{f})(T-t)}$, the forward price of the currency pair, the formulas above can be simplified to

Thus one only needs the discount rate in the domestic currency.

III. Example

Consider a call on